
From Labour Arbitrage to High-Value Digital Outcomes
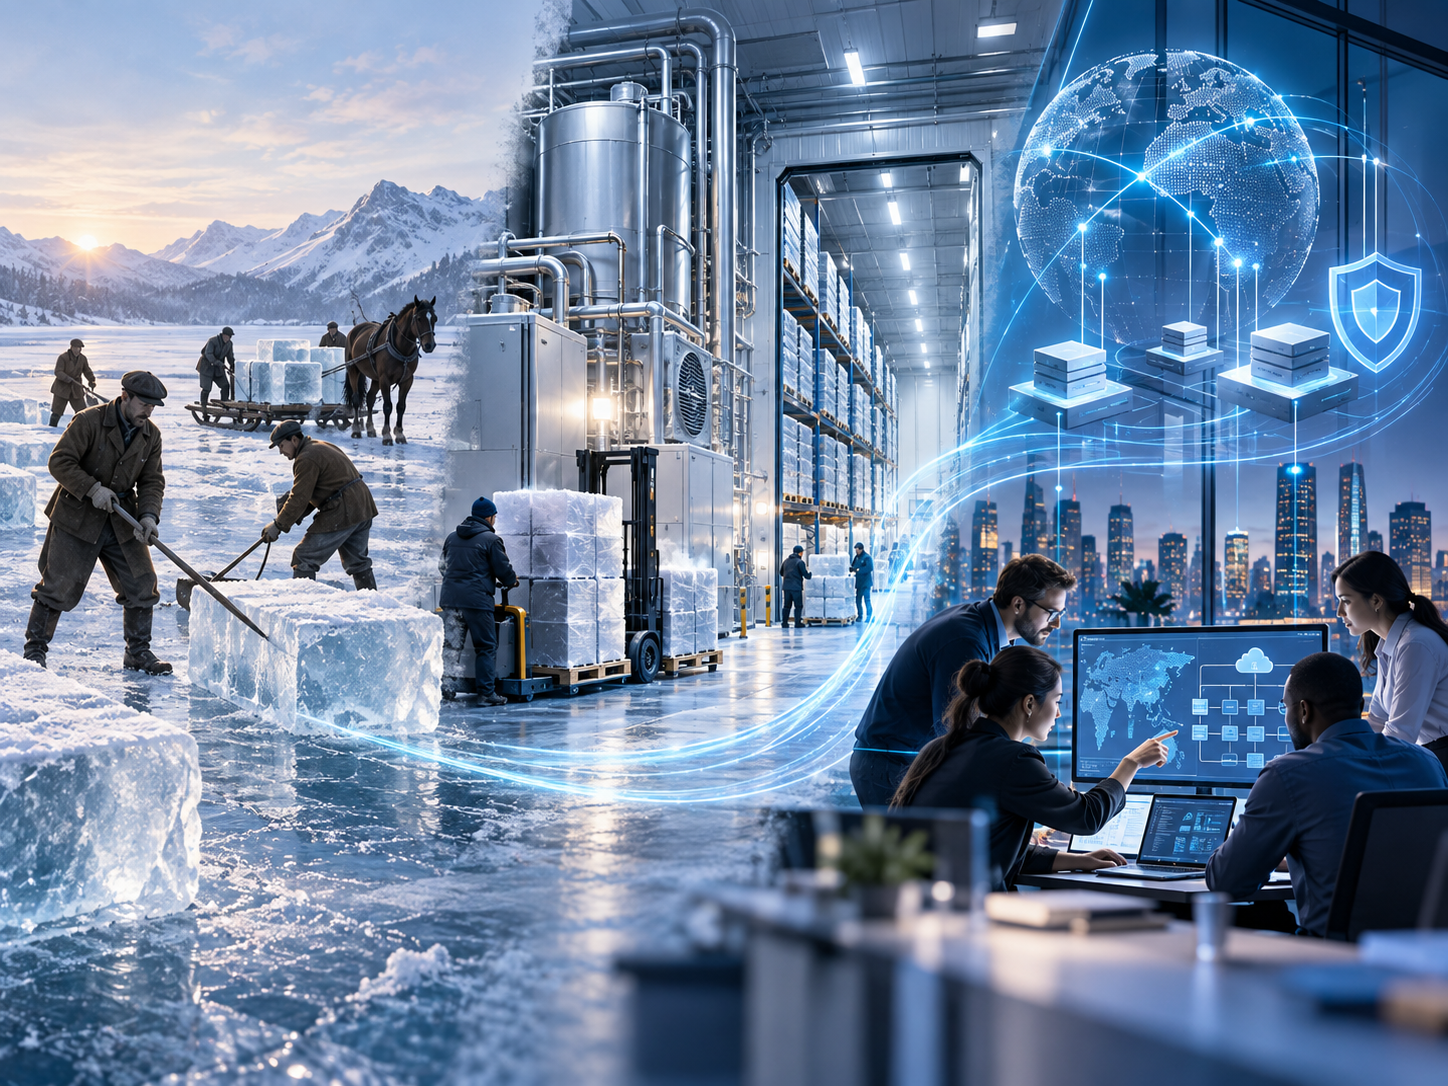
The history of the ice industry offers a useful analogy for what is now happening in IT services. In the first era of the industry, businesses harvested natural ice from frozen lakes and transported it to customers. In the second, industrial ice plants manufactured ice locally, removing the need to depend on geography and seasons. In the third, refrigeration moved directly into homes and businesses, fundamentally changing the market again. At each stage, the customer need remained broadly the same i.e., keeping things cold, but the technology used to satisfy that need changed dramatically. Companies that defined themselves narrowly by the existing production method were displaced, while those that understood the underlying customer need and adapted to the new technology survived and prospered.
IT service industry now faces a similar transition. For decades, the industry has been built around a relatively simple equation: technology change required large numbers of skilled people, and providers created value by supplying those people more efficiently than clients could themselves. Global delivery models, offshore development centres, specialist engineering practices and large transformation programmes all grew from this assumption. Artificial intelligence is now beginning to undermine it. Coding, testing, documentation, analysis and many other activities that historically consumed significant human effort can increasingly be accelerated or partially automated. As AI-assisted engineering matures further, the amount of labour required to create and maintain software will fall, while the value of judgement, architecture, domain knowledge and orchestration will rise.
The lesson from the ice industry is not that demand disappears when technology changes. People still needed cooling. They simply stopped buying it in the same way. Likewise, organisations will continue to need technology transformation, secure systems, integrated data, digital products and reliable operations. What is changing is where value sits. Providers that continue to define themselves primarily by the number of engineers they can deploy risk becoming the equivalent of industrial ice harvesters in the age of home refrigeration. Those that reposition themselves around outcomes, architecture, product thinking, specialist domain expertise and highly capable multidisciplinary teams can move into a significantly more valuable role. The challenge, therefore, is not simply to adopt AI tools. It is to redesign the IT services business model around a world in which software production itself is becoming dramatically easier.
There are 5 steps that an IT services company can take to stay relevant to its customers and embrace the AI opportunity.
From Time and Materials to Outcomes
The first change must be commercial. Time-and-materials models made sense when effort was closely correlated with value. If a programme required 50 engineers for two years, suppliers could price the engagement around the cost of those people, add margin and manage utilisation. AI increasingly breaks that relationship. If a supplier can use automation and AI-assisted development to complete the same work with 20 people, continuing to charge for 50 creates an obvious tension between customer value and supplier economics. In effect, productivity improvement becomes commercially inconvenient because reducing the effort required also reduces revenue.
Outcome-based models reverse that incentive. Instead of buying developer days, clients buy a measurable improvement: a service launched by a particular date, a percentage reduction in processing costs, increased automation, improved system availability, faster release cycles or the retirement of a legacy platform. The provider is then rewarded for finding the most efficient way of achieving the result. AI becomes economically attractive because every productivity gain can improve delivery speed, margin or both. This also encourages suppliers to reuse intellectual property, automate processes and continuously improve the delivery model rather than maximising billable effort.
The shift does not mean that every engagement needs to become a rigid fixed-price contract. Outcomes can be structured through milestone payments, shared savings, transaction pricing, platform subscriptions, service-level commitments or gain-share mechanisms. The important principle is that commercial value should increasingly be linked to what has been achieved rather than how many people have been deployed. This creates much stronger alignment between client and supplier and is particularly important in an AI environment, where the effort required to achieve a given result may change significantly during the life of a programme.
Move Up the Technology Value Chain
As the cost of software production falls, differentiation moves higher up the value chain. Writing code is only one part of solving a business problem, and often not the most difficult part. Large organisations are constrained by complex technology estates, poorly integrated platforms, duplicated data, accumulated technical debt, regulatory requirements, security vulnerabilities and decades of architectural decisions. Generating software faster does not automatically resolve any of these problems. In many cases, the ability to produce software more rapidly could make them worse by allowing organisations to create even more fragmented applications and services.
The strategic opportunity for IT services companies is therefore to become much stronger in enterprise architecture, integration, governance and cybersecurity. Clients will increasingly need partners that can determine where AI should be used, which systems should be modernised or retired, how data should move across organisational boundaries, where human oversight must remain, and how increasingly autonomous systems can operate safely. These disciplines require judgement, organisational context and technical leadership rather than simply engineering capacity.
Architecture becomes particularly important because AI lowers the barrier to creating applications. When almost every business team can generate software, the risk of uncontrolled technology proliferation increases. Integration also becomes more valuable because AI agents and new digital products must interact with existing systems of record, APIs, data stores and business processes. Governance becomes essential as organisations seek to control data usage, model behaviour, regulatory compliance and accountability. Security must evolve from protecting relatively static applications to managing environments in which AI systems may independently access data, invoke services and make decisions. IT services providers that develop deep capabilities in these areas will increasingly occupy the trusted-adviser position that traditional systems integrators once held through sheer scale.
Make Product Management a Core Technology Capability
A second capability that becomes significantly more important in the AI era is product management. Traditional IT services delivery has frequently been organised around projects: requirements are specified, a team is assembled, software is built, the project concludes and responsibility moves elsewhere. AI accelerates the need to move away from that mindset because digital services will increasingly evolve continuously. New capabilities can be prototyped and released quickly, customer behaviour can be measured rapidly and features can be adapted without waiting for lengthy development cycles.
Strong product management ensures that faster engineering translates into better business outcomes rather than simply more features and functionality. Product managers define the problem worth solving, understand user needs, prioritise competing demands and determine whether investment is delivering measurable value. As engineering becomes faster, the ability to decide what not to build becomes as important as the ability to build it. Without strong product leadership, organisations risk using AI to accelerate low-value activity.
For IT services companies, product management should therefore become part of the core delivery proposition rather than something left exclusively to the client. Providers should develop people who can combine market insight, service design, technology understanding, data and commercial thinking. These product leaders should remain responsible for outcomes over time rather than merely translating requirements into backlogs. The strongest providers will increasingly behave less like outsourced development organisations and more like product companies working alongside their clients.
Develop Super-Specialist Domain Expertise
As generic technology capability becomes easier to access, domain expertise becomes a much stronger source of competitive advantage. A developer equipped with modern AI tools may be able to create applications across many industries, but understanding the underlying business problem remains difficult. Healthcare, defence, banking, insurance, government, energy and other complex sectors contain specialist processes, regulatory frameworks, data structures, operating constraints and institutional knowledge that cannot easily be acquired through generic engineering capability.
IT services companies should therefore deliberately develop what might be described as super-specialist domain expertise. This goes beyond broad labels such as “public sector” or “financial services”. It means understanding specific problems deeply enough to bring pre-existing knowledge, architectures, workflows and reusable solutions to them. In government, that might mean deep expertise in benefits administration, tax, border operations or case management. In banking, it could mean fraud detection, lending, payments or regulatory reporting. In healthcare, it may involve clinical pathways, patient administration or interoperability standards.
This expertise allows the supplier to start further ahead. Instead of spending months learning the client’s environment, teams arrive with informed hypotheses, reference architectures, reusable assets and an understanding of common failure modes. AI can amplify this expertise further by embedding specialist knowledge into reusable agents, accelerators and platforms. The result is a powerful combination: technology becomes increasingly commoditised, while accumulated domain intelligence becomes more valuable and more scalable.
Re-engineer the Workforce Around Multi-Skilled Teams
Perhaps the most difficult transformation will be organisational. Traditional IT services companies have created highly segmented career structures: business analysts gather requirements, architects design solutions, developers write code, testers validate it, DevOps teams deploy it and support teams operate it. This specialisation made sense when each activity required substantial manual effort. AI increasingly allows one capable individual to perform activities that previously required several specialist roles.
The emerging model is likely to resemble the Forward Deployed Engineer, or FDE, concept: technically strong individuals who can work directly with customers, understand business problems, design solutions, manipulate data, build prototypes, integrate systems and deploy working technology. They are neither conventional consultants nor narrow software engineers. They combine technical breadth, customer understanding and ownership of outcomes. Rather than handing work between multiple functional silos, a small multidisciplinary team can take responsibility from problem definition through to production.
This does not eliminate the need for deep specialists. Complex organisations will still require outstanding security engineers, architects, data scientists and other experts. But the balance of the workforce changes. Large numbers of narrowly defined roles will increasingly be replaced by smaller numbers of highly capable people supported by AI tools and specialist expertise when required. Career development must therefore focus on breadth as well as depth: engineers need commercial awareness and product skills; consultants need stronger technical capability; architects need to understand data and AI; and delivery leaders need to understand how technology products evolve continuously.
For many established IT services companies, this will be the most disruptive part of the transition because their financial models, recruitment processes, utilisation measures and management hierarchies have been designed around large pyramids of specialised labour. Re-engineering that workforce will require different hiring profiles, different incentives and potentially much smaller teams. A large scale re-training initiative is necessary to reshape existing workforce. The organisations that act early, however, can turn that disruption into an advantage by creating a delivery model that is faster, more accountable and much closer to the customer.
A New Definition of the IT Services Company
The AI era therefore requires something more fundamental than adding generative AI capabilities to the existing IT services catalogue. The industry needs to redefine what it sells and how it creates value. Revenue must become less dependent on the quantity of human effort deployed and more dependent on measurable outcomes. Technology capability must move upward from coding towards architecture, integration, governance and security. Product management must become central to delivery. Generic sector knowledge must evolve into deep specialist expertise, and rigidly segmented workforces must give way to smaller, multidisciplinary teams capable of taking responsibility for an entire problem.
Just as the ice industry experienced, the successful IT services company of the next decade may look very different from the successful providers of the last two decades. It may employ fewer people relative to its revenue, use substantially smaller delivery teams, own more intellectual property and generate more recurring or outcome-linked income. Its strongest people will combine technology expertise, domain understanding, product judgement and customer engagement rather than operating inside tightly defined functional roles. AI will sit underneath this model as an accelerator, but it will not itself be the proposition.
The fundamental shift is from selling technology labour to delivering technology-enabled outcomes. None of this easy or straightforward as technology is changing almost every week, and any internal transformation is both complicated and complex. However, providers that make that transition will find themselves occupying a more strategic and economically valuable position than traditional IT services companies have ever held.